2027 asset management outlook summary:
- Global AuM projected to reach $160 trillion by 2028 (7% annual growth from 2023 baseline of $119T)
- AI transforming operations: automation, risk management, personalized advice. Technology skills now essential for all roles
- Alternative investments expected to capture 57% of global revenues by 2028, up from 54% in 2023
- Passive funds will continue dominating flows but face margin pressure
- ESG investing stabilizing at $3T+ AuM after 2021-2024 correction, shifting toward integrated risk analysis
Career impact: Alternatives hiring accelerating. AI upskilling mandatory. ESG evolving into climate risk specialization. Active specialty roles remain strong.
Planning your asset management career for 2027 and beyond? Understanding where the industry is heading matters more than where it’s been.
Global assets under management are projected to reach $160 trillion by 2028, growing at 7% annually. But this growth masks major shifts: alternatives will capture 57% of revenues, AI is eliminating routine analyst work, and ESG is evolving from standalone strategies into integrated risk analysis.
This guide examines four trends reshaping asset management careers through 2028. Based on research from BCG, PwC, and Morningstar, we analyze what these changes mean for portfolio managers, analysts, ESG specialists, and technologists entering or advancing in the industry.
Asset management outlook: How’s the sector doing?
According to Boston Consulting Group’s latest research, the total assets under management (AuM) in 2025 grew by 11% to $147 trillion globally, with the growth rate higher than historical average of 7% annually for the period 2005-2024.
This is mainly driven by retail investor demand, especially Asia Pacific. In fact, PwC projected that global asset management AuM will continue to grow at 6% annually from 2025 to 2030.

When broken down by region, we can see that most regions delivered positive growth in AuM from 2024-2025.

| Regions | Commentary |
|---|---|
| North America | World’s largest asset management region, with US accounting for over 90% of the region’s AuM. AuM increased by 13%, adding $7.7 trillion in value. This growth is mainly attributable to strong consumer spending, and a historically low unemployment rate. |
| Europe | Also recorded decent AuM growth, increasing by 7% to $30.1 trillion. UK is Europe’s largest market with ~27% market share. Institutional segment (majority of UK market) is the main driver of growth. |
| Japan & Australia | Both countries have collectively grown 12% to $8.8 trillion AuM, mainly due to strong market performance. |
| Asia (excl. Japan & Australia) | Assets in other Asia Pacific countries grew at the same rate of 12% to $29.6 trillion. This growth rate is heavily influenced by China – the second-largest asset management market in the world. Retail segment accounts for 60% of China’s AuM, which recorded a strong growth in 2025, mainly driven by the rise in retail investing. |
| Latin America | Latin America’s AuM grew 17% to $2.8 trillion, with Brazil holding 61% of the region’s AuM. Brazil’s AuM growth is mostly driven by retail investors. |
| Middle East & Africa | Middle East is the largest market in this region with $3.2 trillion AuM. Its 12% AuM growth is mainly driven by strong market performance and recovering oil prices. |
OK, that’s a good start, I hear you say.
So, what are the key trends for the future of asset management?
1) Negative operating leverage: AuM growth no longer translates to higher profitability
Despite global AuM reaching record levels ($147 trillion in 2025), asset managers are grappling with persistent negative operating leverage. Over the past 15 years, global AuM has more than tripled and revenues have more than doubled, yet operating margins remain pinned near 30% – essentially unchanged from where they stood in 2010.

Between 2010-2025, operating costs rose faster (5.4% CAGR) than net revenues (5.1% CAGR), meaning scaling assets no longer automatically expands profitability. Five structural pressures explain why:
- Growth is over-reliant on market appreciation, not organic flows: Over 80% of gross revenue growth in recent years has been driven purely by rising equity and bond markets rather than organic net inflows. This masks an underlying vulnerability: when beta subsides, organic fee growth remains weak.
- Product mix shifts and the rise of Active ETFs: Passive funds continue to dominate inflows, but pressure has intensified as Active ETFs gain rapid traction. While active ETFs preserve active strategies, they do so at fee levels substantially lower than the traditional legacy mutual funds they cannibalize (charging ~0.64% vs. 1.08% on average).
- Institutional fee compression is relentless: Large asset owners continue demanding sharper pricing, driving a steady ~3% annual decline in institutional fee realizations across standard asset classes.
- Rising operational and technology spend: Traditional scale advantages are being eroded as firms face soaring expenditures in technology, enterprise data feeds, cybersecurity, and regulatory reporting infrastructure. Technology spend has surged from a historic ~5% toward 15% of total operating expense budgets.
- Distribution bottlenecks and commoditization: Investment product manufacturing has become heavily commoditized. Gatekeepers—such as centralized wealth platforms, model portfolio aggregators, and digital brokers—control client shelf space and extract a growing share of the industry’s economic value, leaving undifferentiated fund launches struggling to gather viable seed assets.
2) How artificial intelligence (AI) is transforming asset management
AI is moving from experimental pilots into everyday use across asset management, reshaping operations, investment research, and client service:
Operational Efficiency & Cost Savings:
- Back-Office Automation: Cuts down routine tasks like trade reconciliation, corporate actions, and compliance checks. BCG estimates that mature AI adoption can reduce operating costs by 25% to 35% in key functions.
- Smarter Risk Management: Automates stress tests, monitors market exposure in real time, and spots liquidity bottlenecks before they become an issue.
- Faster Data Processing: Cleans and processes unstructured data—such as earnings calls, company filings, and ESG reports—in seconds rather than hours.
Better Investment Decisions:
- Wider Coverage for Analysts: Acts as an AI assistant, helping fundamental research analysts cover 2x to 5x more companies without needing bigger teams.
- Alternative Data Insights: Evaluates non-traditional datasets (like credit card spending or supply chain signals) to catch market trends early.
- Smarter Execution: Uses machine learning to optimize trade execution, reduce trading costs, and manage factor risks.
Personalized Client Service:
- Custom Portfolios at Scale: Enables wealth managers to quickly build tax-optimized, tailored portfolios for individual client needs.
- Predictive Client Insights: Helps sales teams spot client redemption risks early and see when portfolios need rebalancing.
- Instant Client Support: AI tools draft quick, accurate portfolio performance updates and commentary for client service teams.
Compliance & Monitoring:
- Anomaly Detection: Tracks trades continuously to catch compliance breaches, errors, or unusual trading activity right away.
- Automated Reporting: Generates regulatory reports directly from central systems, saving time and cutting manual errors.
How does the increasing digitization in asset management affect jobs?
- Technology is now a core business driver: Generating strong returns is no longer enough on its own; client portals, data pipelines, and distribution tech are critical to winning business. Asset managers need professionals who understand both investment strategies and scalable technology platforms.
- Sales and client teams need data fluency: The days of relying solely on standard slide decks and personal networks are fading. Client-facing staff must be comfortable using data analytics and CRM insights to understand client behavior, freeing them up to focus on high-touch relationship management.
3) Select alternatives and passives are winners
Since 2005, alternative and passive assets have grown considerably faster, to become more significant parts of portfolios.

Alternatives are expected to continue outpacing traditional products, growing from 50% of total market AuM in 2025 to a projected 54% revenue share by 2030.
The key driver of this growth is investor demand for increased performance, uncorrelated returns, illiquidity premiums, and other nontraditional return profiles, particularly as institutions across the globe face the challenge of a widening gap between assets and liabilities.
Within the alternatives sector – which consists of commodities, infrastructure, private debt, hedge funds, real estate and private equity – the main growth driver is the private debt and private equity sectors. They are expected to generate 70% of total revenue of alternatives by 2030.
Hedge funds, by contrast, have seen their asset growth decline as overall returns over the past decade have trailed the S&P, although capital still flows disproportionately into the larger funds (AuM > $5 billion) as investors prioritize reputation and track record.
For those interested in further specializing in alternative investments, it is worth checking out the CFA Program (with Private Markets Specialized Pathways), or the Chartered Alternative Investments Analyst (CAIA) designation.
For CAIA, if you happen to be a CFA charterholder, you can get exemptions to CAIA Level 1 to sit for CAIA Level 2 (final exam) to obtain a CAIA charter.

Meanwhile, passive investments are projected to maintain growth momentum through 2030, continuing to capture 60-70% of net flows despite margin pressure. The separation between alpha and beta will accelerate as investors increasingly allocate to low-cost passive products for core exposure whilst paying for active management only in specialized strategies.
The increased share of passive investments is driven by both institutional and retail investors’ demands. The separation between alpha and beta will accelerate as investors increase their investment allocation to passive products in search of low fees and broad beta market exposure.
So how does the growth in alternative and passive assets affect asset management jobs?
1) While there is generally a reluctance by firms to change Portfolio Managers (PMs) for fear of triggering huge outflows, PMs cannot afford to be complacent. The growth of passive investments, artificial intelligence and computer-driven investment styles are headwinds to watch out for.
2) While passive investments are rising in popularity, this doesn’t mean active is “out” though. While active core products are declining in market share and revenues, active specialty products (e.g. sectors, small/mid caps, emerging markets, high yield, convertibles) is still expected to hold its market share, although it continues to experience price pressure in the future.
3) Hiring opportunities in alternative investments – especially private equity, infrastructure, private debt and real estate – is expected to increase in the next 5 years.
4) ESG investing is experiencing a bumpy road
The meteoric rise of Environmental, Social, and Governance (ESG) investing, which peaked in 2021 with a staggering $627 billion in global net inflows, has encountered significant headwinds.
After inflows plummeted to $34 billion in 2024, ESG investing is expected to stabilize and evolve rather than grow explosively. Industry forecasts suggest ESG will shift from standalone products toward integrated climate risk analysis across all portfolios by 2028, with regulatory mandates (particularly in Europe and UK) driving demand for ESG expertise.
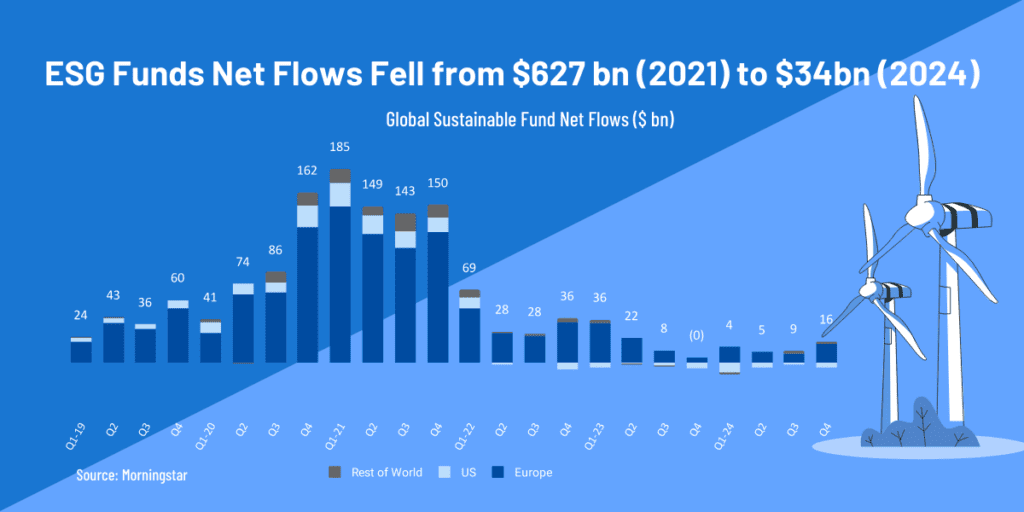
This dramatic shift is particularly evident in regional disparities, with the US experiencing substantial outflows, while Europe and the rest of the world see reduced, but still positive, inflows.
Despite this, global ESG assets under management have continued to grow, reaching a substantial $3 trillion in 2024, indicating a complex landscape where asset growth and investor sentiment diverge.

Several factors have contributed to this “bumpy road” for ESG investing:
- Concerns About Misleading Claims: Increased scrutiny has revealed instances of “greenwashing,” where funds overstate their ESG credentials, eroding investor trust and creating skepticism about the genuine impact of ESG products.
- Performance Pressures in Volatile Markets: During recent market downturns, ESG funds, often heavily weighted in growth sectors, have underperformed compared to traditional energy stocks. This has challenged the perception that ESG investing consistently delivers superior returns.
- Political Debates and Differing Priorities: In the US, ESG has become a subject of political debate, with concerns about energy security and opposition to certain corporate agendas impacting investor sentiment.
- Lack of Clear and Consistent Standards: The absence of universally accepted ESG metrics and reporting standards makes it difficult to compare funds and assess their true impact, creating confusion and hindering widespread adoption.
- Impact of Rising Interest Rates: The global rise in interest rates has caused investors to become more risk-averse, and to focus on short-term returns, rather than the long-term goals of ESG investing.
That said, ESG investing is far from ‘dead’, it does need a moment to adapt to changes. We expect ESG to remain important part of an investment portfolio in years to come:
- Evolving Regulatory Expectations: Despite political headwinds, regulatory frameworks are pushing for greater transparency and accountability in ESG investing.
- Growing Corporate Focus on Sustainability: Companies are increasingly integrating ESG factors into their business strategies, driven by stakeholder pressure and the long-term benefits of sustainable practices.
- Potential for Long-Term Value: Many believe that ESG factors are essential for long-term value creation, as companies that effectively manage ESG risks and opportunities are better positioned to succeed.
- Influence of Changing Investor Preferences: Younger generations are increasingly prioritizing sustainability in their investment decisions, and their preferences will shape the future of ESG investing.
What does the projected growth in ESG investing mean for jobs?
These changes in sustainable investing has created new roles within asset management:
1) a pure stewardship/governance role which offers an alternate route into the asset management industry for those that come from a non-investment, but more policymaking or natural sciences background.
2) an experienced investment/research role which focuses on ESG issues at a sector level, making recommendations across asset classes and articulate what ESG considerations the team should take. For existing experienced investment professionals with strong interest in responsible investments, this offers a route to shift to a more ESG-centric role within the firm.
3) As impact investing gains traction, there will be increased demand for professionals skilled in measuring and reporting the social and environmental impact of investments. This includes roles related to impact assessment, impact reporting, and impact investing strategy.
4) The need for robust ESG data and analysis will drive demand for professionals skilled in data collection, interpretation, and reporting. As regulatory requirements and investor scrutiny increase, expertise in ESG metrics and frameworks becomes essential.
For those interested in upgrading your knowledge in ESG and climate change matters, do check out these relevant global qualifications which currently can be done remotely:
– Sustainable Investing Certificate by CFA Institute,
– Certified ESG Analyst (CESGA) by EFFAS,
– Certificate in Climate and Investing by CFA UK,
– Sustainability & Climate Risk (SCR) Certification by GARP
So, what have we learned?

The asset management industry is navigating a structural transition. While rising markets have pushed assets under management to historic highs, firm profitability remains constrained by persistent fee compression, elevated technology expenditures, and the rapid migration of capital into lower-cost passive and active ETF vehicles.
To thrive in this environment, firms are actively breaking down the historical divide between core investment functions and technology. The most valuable professionals are no longer pure traditional generalists or isolated coders; rather, the industry is prioritizing hybrid talent—individuals who combine rigorous financial acumen, deep sector knowledge, and strong interpersonal advisory skills with the ability to harness AI and alternative datasets across day-to-day operations.
Ultimately, market expansion alone will no longer mask inefficient operational models. Those who embrace continuous technical upskilling, target specialized or private-market asset classes, and focus on delivering high-conviction client value will be best positioned to advance their careers.
Asset management careers & trends FAQs
AI will not replace portfolio managers, but it is fundamentally altering their daily responsibilities. AI excels at processing complex datasets, backtesting scenarios, and automating routine screening, while strategic portfolio construction, risk judgment, and client relationship management remain human-led.
The primary structural impact is occurring at the entry and junior levels: routine data-gathering and basic financial modeling are increasingly automated, prompting many firms to streamline junior analyst intakes while requiring incoming talent to possess immediate data literacy and AI fluency.
The strongest hiring momentum remains concentrated in alternative investments and specialized private markets, where fee margins are more resilient:
– Private Debt & Direct Lending: Underwriters and credit analysts.
– Infrastructure & Real Assets: Specialists focused on energy transition and digital infrastructure.
– Private Equity Operations: Value-creation and portfolio operations teams.
– Active ETF Product Specialists: Structuring and capital markets professionals bridging active strategies with ETF distribution.
– Wealth Platform Distribution: Relationship managers targeting high-net-worth individual (HNWI) wealth channels.
Yes, provided you align with the industry’s shift away from generic marketing toward technical integration:
– Focus on Climate Risk & Regulatory Reporting: High demand remains for expertise in mandatory disclosures (such as SFDR and CSRD), transition finance, and emissions auditing.
– Embed Sustainability into Core Analysis: The most durable career path is combining traditional fundamental credit or equity valuation with climate and governance risk analysis, rather than relying exclusively on standalone, non-financial ESG marketing roles.
Traditional asset managers are adapting by vacating easily replicated, high-fee core products and concentrating their resources where true alpha can be defended:
– Specialized & Less Liquid Strategies: Emerging market debt, small/mid-cap equities, high-yield credit, and private credit.
– Active ETF Structures: Repackaging high-conviction alpha strategies into tax-efficient, transparent, and lower-cost vehicle formats.
– Direct Indexing & Customization: Offering bespoke, tax-managed portfolio solutions directly to wealth clients.
Investment professionals do not need to become software engineers, but operational tech literacy is now essential:
– Data Fluency: Comfort working with large, diverse data feeds and utilizing modern analytics packages.
– AI Tool Integration: Effective prompt engineering and leveraging generative AI models to accelerate earnings analysis and company screening.
– Client-Facing Translation: The ability to clearly explain quantitative, algorithmic, or AI-assisted investment rationales to institutional clients and allocators.
Junior rotational programs have become more selective as AI and automated platforms absorb routine filings, boilerplate memos, and basic statement updates.
To stand out, early-career analysts must build deep sector-specific insight, develop relationships with management teams and industry experts, and master non-traditional data interpretation early in their careers.
What do you think of these upcoming changes? How do these trends affect your current career planning? Would be great to hear your comments below!
Meanwhile, here are some related articles that may be of interest:
- Why Is ESG Important & Which Careers Can Benefit From It?
- What Does An ESG Analyst Do & How To Become One
- Complete Guide to ESG Certifications & Courses
- How To Correctly Display Your CFA Program Status On Your Resume, LinkedIn & Business Cards
- What Are Typical Career Paths for CFA Charterholders?
- Switch Finance Jobs Effectively With Our Career Change Planner
- The CFA Charter is Not a Golden Ticket to Jobs – But Here’s How It Can Help
Very insightful – thank you.
My pleasure George – what part in particular you found interesting? Are you currently in the AM sector, or looking to move into it?
i’m looking to move into it