The CPA exam is the gateway to one of the most respected professional designations in US accounting. This guide covers everything a candidate needs – exam structure, pass rates, requirements, costs, and career outcomes – with current 2026 data throughout.
Quick summary
- The CPA exam (Certified Public Accountant) consists of 4 sections: 3 mandatory Core sections (AUD, FAR, REG) plus 1 Discipline section of your choice (BAR, ISC, or TCP)
- Passing score is 75 on a scaled scoring system – not a percentage of questions answered correctly
- 2025 cumulative pass rates: AUD 48%, FAR 42%, REG 63%, BAR 42%, ISC 68%, TCP 78%
- Most candidates spend 375-500 hours studying across all 4 sections
- The CPA license is issued by individual state boards – requirements vary by jurisdiction
- Total cost including exam fees, study materials, and licensing: typically $1,989-$5,324
Popular articles:
Best CPA Study Materials
Free CPA Study Planner
CPA Exam Dates & Results Day

CPA Pass Rates

How to Pass CPA Exams

How to Focus When Studying
CPA vs CFA

All CPA articles
What is the CPA exam?
The Certified Public Accountant (CPA) designation is the gold standard professional license in US accounting. It is administered by the American Institute of CPAs (AICPA) and the National Association of State Boards of Accountancy (NASBA), and issued by individual state boards of accountancy across 55 US jurisdictions. The CPA license grants the right to sign audit reports, prepare certain tax filings, and offer public accounting services – roles that are legally restricted to licensed CPAs in most states.
As of August 2025, there are 653,408 active licensed CPAs in the United States according to NASBA. That number has been declining slightly since 2019, fluctuating between 654,000 and 678,000, driven by a combination of retirements, reduced accounting program enrollment, and competition from alternative career paths.

The US Bureau of Labor Statistics projects 5% annual growth in accounting demand through 2034 – meaning the supply-demand gap for CPAs is expected to widen, which has contributed to upward salary pressure and significant legislative changes to the licensing pathway.
The most significant of those changes came in 2024 under what AICPA and NASBA call “CPA Evolution” – a restructuring of the exam to a 3 Core plus 1 Discipline format, allowing candidates to demonstrate specialization rather than broad coverage across all content areas. This mirrors the direction taken by other major professional designations and reflects the changing skills required in modern accounting practice.
Related articles:
CPA Exam Costs

Is CPA Worth It?
CPA Salaries

CPA Requirements by State
What sections does the CPA exam have?
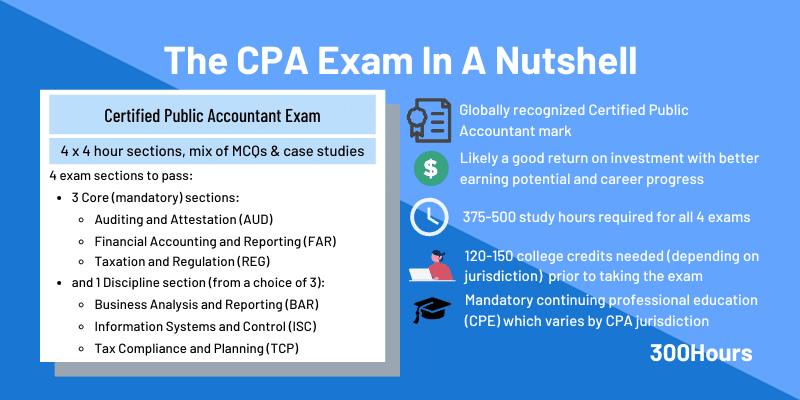
Since CPA Evolution launched in January 2024, the Uniform CPA Exam consists of four sections: three mandatory Core sections that all candidates must pass, and one Discipline section chosen by the candidate. All four sections lead to the same CPA license regardless of which Discipline you choose.
| Section | Type | Duration | Format | Key content areas |
|---|---|---|---|---|
| AUD – Auditing and Attestation | Core | 4 hours | 78 MCQs (50%) + 7 TBSs (50%) | Ethics, risk assessment, evidence, reporting |
| FAR – Financial Accounting and Reporting | Core | 4 hours | 50 MCQs (50%) + 7 TBSs (50%) | Financial reporting, balance sheet accounts, transactions |
| REG – Taxation and Regulation | Core | 4 hours | 72 MCQs (50%) + 8 TBSs (50%) | Federal tax, business law, professional ethics |
| BAR – Business Analysis and Reporting | Discipline (choose 1) | 4 hours | 50 MCQs (50%) + 7 TBSs (50%) | Financial analysis, technical accounting, government |
| ISC – Information Systems and Controls | Discipline (choose 1) | 4 hours | 82 MCQs (60%) + 6 TBSs (40%) | IT systems, cybersecurity, SOC engagements |
| TCP – Tax Compliance and Planning | Discipline (choose 1) | 4 hours | 68 MCQs (50%) + 7 TBSs (50%) | Individual and entity tax compliance and planning |
Multiple choice questions (MCQs) test conceptual knowledge, while task-based simulations (TBSs) test application in realistic scenarios. The 50/50 weighting applies to all sections except ISC, where MCQs carry 60% of the weight.
When can you sit each section?

Core sections (AUD, FAR, REG) are available for continuous testing throughout the year. Discipline sections (BAR, ISC, TCP) are available during a one-month window at the start of each quarter. The table below shows the 2026-2027 testing windows and target score release dates.
| Section | Exam dates | Target score release |
|---|---|---|
| AUD, FAR, REG (Core) | Continuous throughout the year | Typically 1-5 weeks after test date |
| BAR, ISC, TCP (Discipline) – Q3 2026 | 1-31 July 2026 | 11 September 2026 |
| BAR, ISC, TCP (Discipline) – Q4 2026 | 1-31 October 2026 | 15 December 2026 |
| BAR, ISC, TCP (Discipline) – Q1 2027 | 1-31 January 2027 | 14 March 2027 |
| BAR, ISC, TCP (Discipline) – Q2 2027 | 1-30 April 2027 | 16 May 2027 |
| BAR, ISC, TCP (Discipline) – Q3 2027 | 1-31 July 2027 | 11 September 2027 |
| BAR, ISC, TCP (Discipline) – Q4 2027 | 1-31 October 2027 | 16 December 2027 |
For the full schedule for 2026-2027 remaining windows, see our CPA exam dates and score release guide.
What is the credit window?
Once you pass your first section, you have a rolling window to pass the remaining three before your earliest credit expires. Most states use a 30-month window measured from the score release date.
Indiana, South Carolina, and Washington extend this to 36 months. Hawaii uses an 18-month window measured from the exam date rather than score release. Louisiana and Wyoming also use the exam date as the starting point for their 30-month window. Check your specific state’s rules at our CPA requirements by state guide.
Related articles:

General CPA Requirements
CPA Results Dates

CPA Career Paths

CPA Exam Order
What are the CPA exam pass rates?
The passing score for each section is 75 on a 0-99 scaled scoring system. A score of 75 does not mean 75% of questions answered correctly – it is a fixed standard of competence calibrated to ensure consistency across different exam versions. The exam is not curved; a higher pass rate means candidates are better prepared, not that the exam has become easier.
Here are the quarterly and cumulative pass rates since CPA Evolution launched in January 2024:
| Quarter | AUD | FAR | REG | BAR | ISC | TCP |
|---|---|---|---|---|---|---|
| Q1 2024 | 45% | 42% | 63% | 43% | 51% | 82% |
| Q2 2024 | 47% | 41% | 63% | 40% | 58% | 76% |
| Q3 2024 | 48% | 40% | 63% | 40% | 62% | 73% |
| Q4 2024 | 44% | 37% | 60% | 34% | 56% | 72% |
| 2024 cumulative | 46% | 40% | 63% | 38% | 58% | 74% |
| Q1 2025 | 44% | 42% | 62% | 38% | 61% | 75% |
| Q2 2025 | 49% | 44% | 64% | 47% | 72% | 81% |
| Q3 2025 | 50% | 43% | 66% | 40% | 67% | 77% |
| Q4 2025 | 49% | 40% | 61% | 40% | 67% | 77% |
| 2025 cumulative | 48% | 42% | 63% | 42% | 68% | 78% |
| Q1 2026 | 48% | 43% | 67% | 41% | 67% | 79% |
Source: AICPA quarterly pass rate releases. BAR, ISC, and TCP introduced January 2024 under CPA Evolution.
Several patterns are worth noting from the data:
- Q4 is consistently the weakest quarter across most sections – candidates sitting in October-December tend to be less prepared on average than those sitting earlier in the year.
- TCP leads all sections with the highest pass rate, making it a popular Discipline choice regardless of candidate background.
- FAR and BAR remain the two toughest sections year-on-year, both requiring the deepest technical knowledge.
- ISC has shown the strongest improvement trend, climbing from 51% in Q1 2024 to 68% cumulative in 2025 as candidates and prep providers adapt to the section.
Pass rates improved across nearly every section in 2025 compared to 2024. AICPA attributes this to candidates and prep providers becoming better calibrated to the CPA Evolution format rather than any change in exam difficulty. We expect further stabilization through 2026 as the format matures.
For the full pass rate analysis with historical trends, see our CPA pass rates guide.
What are the CPA requirements?

CPA licensing is state-specific – there is no single national CPA license. Each of the 55 US jurisdictions (50 states plus DC, Puerto Rico, Guam, USVI, and CNMI) sets its own requirements for education, experience, ethics, and fees. The common framework across all jurisdictions is the “4 Es”: Education, Exam, Experience, and Ethics.
The traditional education requirement is 150 semester hours plus a bachelor’s degree. As of July 2026, however, over half of all US jurisdictions have enacted an alternative pathway allowing licensure with a standard bachelor’s degree (120 hours) plus additional work experience – replacing the extra year of coursework.
- States including Alaska, Ohio, Oregon, Minnesota, South Carolina, and West Virginia are among those where this pathway is now active.
- California, New York, Florida, and Pennsylvania are among the states still requiring 150 hours.
The experience requirement is typically 1-2 years of qualifying supervised work under a licensed CPA, and around 40 states require a professional ethics exam before licensure. For full requirements in your specific state, see our CPA requirements by state guide covering all 55 jurisdictions, or the CPA requirements overview for the full five-step process.
How much does the CPA exam cost?

CPA exam costs have two layers: the NASBA section fee, which is uniform across all 55 jurisdictions, and state-specific application and registration fees, which vary.
From 4 July 2026 (or 1st August 2026 for some jurisdictions), the NASBA section fee is $268.59 per section ($1,074.36 for all four). On top of this, most states charge a one-time education evaluation fee ($96 in most CPAES states) and a per-section registration fee ($96 in most CPAES states), bringing the standard CPAES total to $1,554.36 for four sections.
| Cost component | Typical amount |
|---|---|
| NASBA section fee (4 sections) | $1,074.36 |
| Education evaluation + registration (standard CPAES state) | $480.00 |
| Standard CPAES total (4 sections) | $1,554.36 |
| Ethics exam (if required) | $250-$320 |
| Study materials (full review course) | $800-$2,500 |
| Initial CPA license application | $35-$650 |
| Realistic all-in total | $1,989-$5,324 |
State fees vary significantly – Texas candidates pay approximately $1,154 total for four sections while New Hampshire candidates pay approximately $1,854. For the full state-by-state fee breakdown, see our CPA exam cost guide.
Related articles:
Free CPA Study Planner
How to Pass CPA Exams
CPA Exam Order
Accounting Career Path
How do you prepare for the CPA exam?
Most candidates spend 375-500 total study hours across all four sections. FAR typically requires the most time due to its breadth; TCP and REG require less for candidates with strong tax backgrounds.
A realistic approach is 6-10 weeks of focused preparation per section, studying one section at a time rather than spreading effort across multiple sections simultaneously.
The most important cost-control decision in the CPA journey is choosing the right review course and sitting sections only when genuinely ready. Every failed attempt costs $364.59 in exam and registration fees, plus study time.
- For provider comparisons, see our best CPA study materials guide.
- Use our free CPA study planner to build a realistic schedule before committing to exam dates.
- See this article for top 10 sage advice from previous CPA candidates and our CPA exam day checklist for helpful reminders before your big day.
What careers does the CPA open up?

The CPA designation unlocks a broad range of roles across public accounting, corporate finance, government, and consulting. The salary premium over non-CPA accountants is well-documented and tends to increase with seniority.
| Sector | Type of work | Typical salary range |
|---|---|---|
| Public accounting – audit | Examining financial records for accuracy and compliance | $50,000-$70,000 (entry); $80,000-$150,000+ (senior/manager) |
| Public accounting – tax | Tax return preparation and planning for individuals and businesses | $50,000-$70,000 (entry); $80,000-$150,000+ (manager/specialist) |
| Corporate accounting | Financial reporting, analysis, and performance management | $60,000-$100,000 (analyst/accountant); $100,000-$200,000+ (controller/CFO) |
| Management accounting | Internal financial analysis and decision support | $60,000-$100,000; $150,000+ in senior management roles |
| Government accounting | Federal, state, or local agency roles | $70,000-$120,000 (mid-career) |
| Forensic accounting | Financial crime investigation and fraud examination | $70,000-$150,000+ |
| Consulting | Financial advisory and business guidance | $70,000 (entry) to $200,000+ (senior/partner) |
For a detailed breakdown of CPA salaries by role, experience level, and location, see our CPA salary guide.
Related articles:
CFA vs CPA

CPA vs CMA

CPA vs EA

CPA vs MBA
How does the CPA compare to other qualifications?
The CPA is a US professional license, not a globally portable designation. Understanding how it compares to other credentials helps candidates decide whether it is the right path for their career goals.
| Qualification | Focus | Ideal for | Key difference from CPA |
|---|---|---|---|
| CFA (Chartered Financial Analyst) | Portfolio management, valuation, investments | Asset management, equity research, private equity | Investment management focus vs CPA’s audit, tax, and accounting |
| MBA (Master of Business Administration) | Business management, strategy | Leadership and general management roles | Broad business education vs specialized accounting license |
| CFP (Certified Financial Planner) | Financial planning, investment advice | Personal financial planning | Client financial planning focus vs CPA’s audit and compliance |
| CMA (Certified Management Accountant) | Internal management accounting | Corporate financial management | Internal reporting focus vs CPA’s external audit and public practice rights |
| ACCA/ACA | International accounting standards | Global accounting roles | Internationally portable vs CPA’s US-specific practice rights |
| Tax lawyer | Tax law, legal representation | Complex tax litigation | Legal expertise vs CPA’s accounting and compliance focus |
For a deeper comparison, see:
Frequently asked questions
What is the CPA exam?
The CPA exam is the Uniform Certified Public Accountant Examination, a four-section professional licensing exam administered by the AICPA and NASBA. Passing all four sections, along with meeting education, experience, and ethics requirements, qualifies candidates for a CPA license issued by their state board of accountancy.
The CPA license is required to sign audit reports and offer certain public accounting services in the US. As of August 2025, there are 653,408 active licensed CPAs in the US.
How many sections does the CPA exam have?
The CPA exam has four sections:
- three mandatory Core sections (AUD – Auditing and Attestation, FAR – Financial Accounting and Reporting, and REG – Taxation and Regulation) plus
- one Discipline section chosen by the candidate from BAR (Business Analysis and Reporting), ISC (Information Systems and Controls), or TCP (Tax Compliance and Planning).
All four sections lead to the same CPA license regardless of which Discipline is chosen. Each section is four hours long and consists of multiple choice questions and task-based simulations.
What is a passing score on the CPA exam?
The passing score for each CPA exam section is 75 on a 0-99 scaled scoring system. This is not a percentage of questions answered correctly – it is a statistically calibrated standard of competence that ensures consistency across different exam versions.
The exam is not curved; your score is independent of how other candidates perform. A higher pass rate in any quarter reflects better candidate preparation, not an easier exam.
How long do you have to pass all four CPA exam sections?
Most US states allow 30 months from the score release date of your first passed section to pass the remaining three. Indiana, South Carolina, and Washington extend this to 36 months. Hawaii uses an 18-month window measured from the exam date. Louisiana and Wyoming also use the exam date (rather than score release) as the start of their 30-month window.
If the window expires before you pass all four sections, your earliest credit lapses and must be retaken. Check the specific rule for your state at our CPA requirements by state guide.
Is the CPA exam hard?
The CPA exam is genuinely one of the most demanding professional licensing exams in the US. The 2025 cumulative pass rates were 48% for AUD, 42% for FAR, 63% for REG, 42% for BAR, 68% for ISC, and 78% for TCP – meaning the average Core section pass rate is around 51%.
That said, pass rates have improved steadily since CPA Evolution launched in 2024 as candidates and prep providers adapt to the new format. Most candidates who prepare thoroughly with a structured study plan and quality review materials pass all four sections within 12-18 months.
What is the difference between the CPA Core and Discipline sections?
The three Core sections (AUD, FAR, REG) are mandatory for all CPA candidates and cover the foundational knowledge required of all licensed CPAs: auditing standards, financial reporting, and taxation and regulation.
The Discipline section allows candidates to demonstrate deeper knowledge in one specialized area – business analysis and reporting (BAR), information systems and controls (ISC), or tax compliance and planning (TCP).
Regardless of which Discipline section a candidate chooses, the CPA license granted is identical with the same rights and responsibilities.
Related articles:
- CPA Requirements by State: Compare All 55 Jurisdictions
- CPA Requirements: How to Become a CPA in 5 Steps
- CPA Exam Cost (2026): $268.59 Per Section, All Fees Explained
- CPA Pass Rates: How Hard Is the CPA Exam?
- CPA Salary: What Can You Expect to Earn?
- Best CPA Study Materials: All Providers Compared
- CPA Exam Dates and Score Release: 2026 Master Plan
- How to Pass the CPA Exam: Your Complete Game Plan
- CFA vs CPA: Which Is Right for You?